Buying Guides
Under-Construction vs Ready-to-Move: Which Should You Buy in 2026?
The 15–25% launch discount vs zero construction risk — a decision framework with the GST math, risk table and the five cases where each side clearly wins.
By the PropertyNivesh Research Desk · Edited by Rakesh Mahajan · · 10 min read
The trade in one sentence
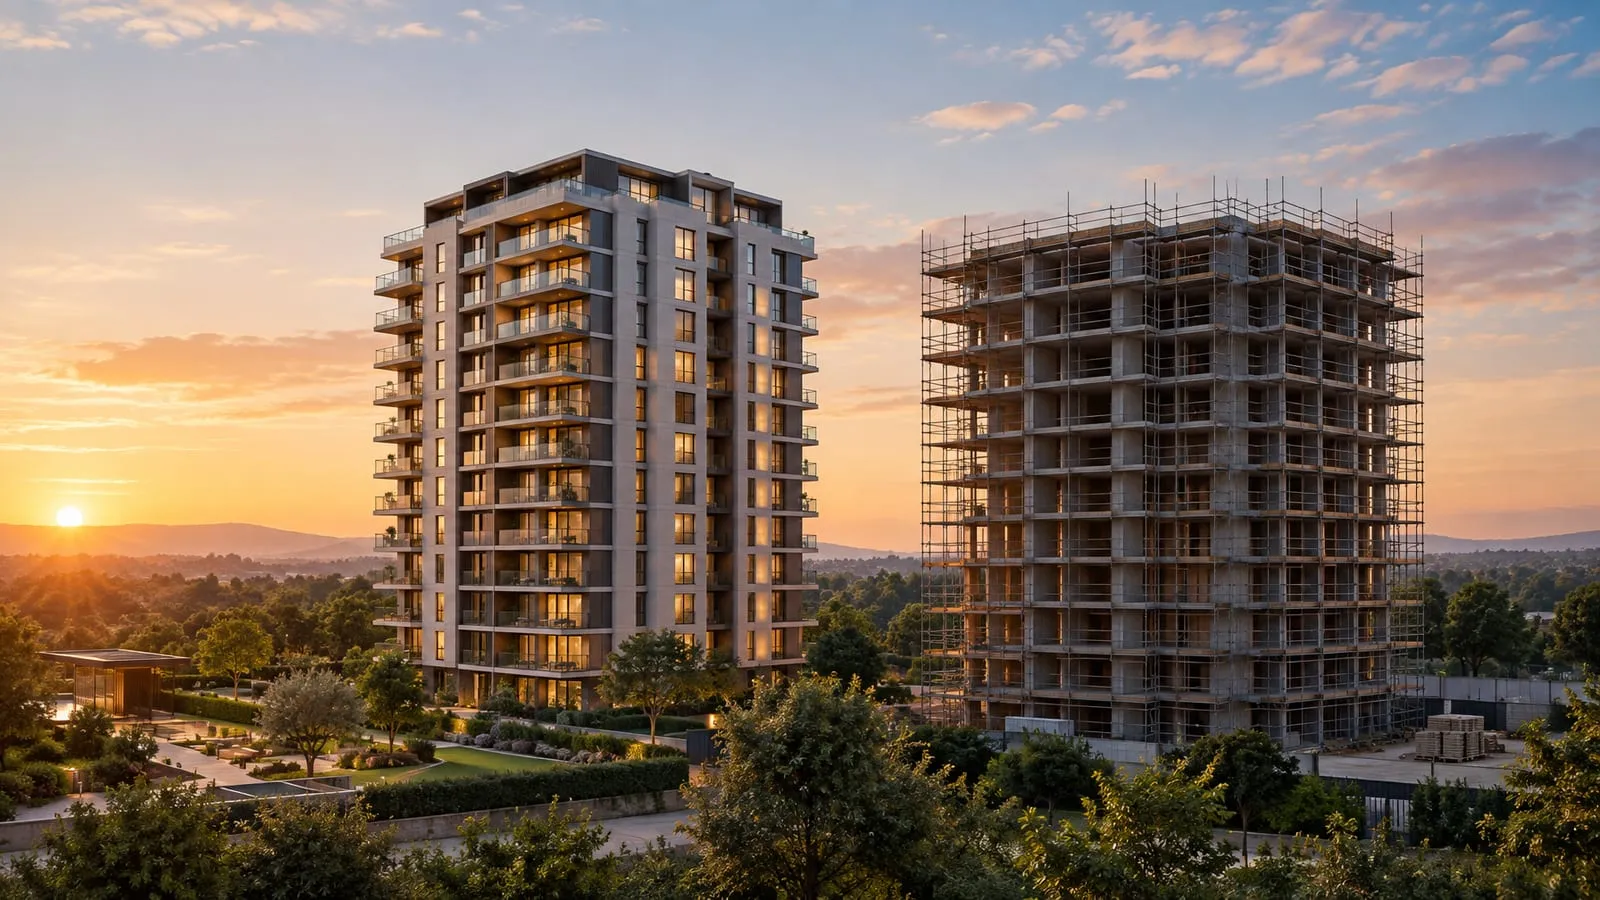
Under-construction (UC) property sells you a discount in exchange for risk and time; ready-to-move (RTM) sells you certainty at a premium. Everything else — GST, payment plans, appreciation math — is detail hanging off that single trade. The mistake most buyers make is choosing by temperament (optimists buy UC, worriers buy RTM) instead of by situation. This guide replaces temperament with a framework.
The full cost-and-risk comparison
| Factor | Under-construction | Ready-to-move |
|---|---|---|
| Entry price | 15–25% below comparable RTM | Full market price |
| GST | 5% (no input credit) | None (with OC) |
| Construction risk | Real — delays, spec dilution, worst-case stall | Zero |
| What you inspect | Sample flat + renders | The actual unit, sunlight, neighbours, society |
| Rent + EMI overlap | 2–4 years of double burden | None — move in or let out immediately |
| Payment structure | Construction-linked (capital-efficient) | Lump sum / full loan draw |
| Appreciation potential | Higher (launch-to-possession uplift) | Corridor-average |
| Customisation | Sometimes possible pre-fit-out | Retrofit only |
Note the arithmetic: the UC discount (say 20%) minus GST (5%) minus the double burden (typically 8–12% of price over the wait) leaves a thinner true edge than brochures imply. UC wins financially only when the project delivers on time — which is precisely the variable buyers control least and builders control most.
When under-construction clearly wins
- Your builder is balance-sheet elite (DLF, Birla, Sobha, Godrej class) — the delay tail-risk that ruins UC math is largely removed
- You're buying 3–5 years ahead of need (children's schooling, retirement return) — the timeline is a feature, not a bug
- A possession-weighted plan exists (e.g., 10:90) — you get launch pricing while the developer carries construction-period risk
- You're targeting a corridor re-rating (metro, expressway) that will complete near your possession date
- Current rent is low relative to the EMI you'd pay on RTM — the double burden is cheap for you
When ready-to-move clearly wins
- You need the home within 24 months — school admissions, marriage, relocation deadlines
- You're an NRI buying remotely — inspectable reality beats renders by more than the discount
- The builder is mid-tier or private with limited disclosure — RTM converts their risk to zero
- You're a rental investor — yield starts immediately, and OC-backed purchase skips GST entirely
- The corridor's re-rating already happened — you'd be paying UC risk for RTM-level appreciation
- Headline environment matters to you: after the ATS/Supertech sagas, sleeping well has a price and RTM is it
The hybrid most buyers overlook: nearly-ready
The best risk-adjusted pocket is often neither: projects 70–90% complete, 6–15 months from OC. Structure is visibly done (the biggest stall risk is behind), pricing still sits 8–12% under RTM comparables, and the double-burden window is short. Our desk's screening rules for nearly-ready:
- Verify progress physically or via RERA QPRs — '90% done' claims deserve photographs
- Confirm the OC application status with the authority, not the sales office
- Check that finishing-stage funding is in place (escrow balance, lender disbursement history)
- Negotiate hard: builders want to close books at this stage and discounts are real
Decision matrix: score yourself
| Your situation | Points to UC | Points to RTM |
|---|---|---|
| Need home within 2 years | — | +3 |
| Top-quartile builder available at launch pricing | +3 | — |
| Buying remotely (NRI) | — | +2 |
| Corridor catalyst completing in 2–4 years | +2 | — |
| Rental yield is the goal | — | +2 |
| 10:90 / possession-weighted plan offered | +2 | — |
| Low risk tolerance after recent headlines | — | +2 |
Final word: in 2026's market — thin luxury supply, heavy mid-market pipelines, and metro catalysts still pending on key corridors — our desk leans RTM/nearly-ready for end-users and quality-UC for investors with 5+ year horizons. And in every single case, the builder's trust score moves the answer more than the completion status does.
The mistakes that turn a good choice bad
- Buying UC for the discount without pricing the double burden — rent plus EMI for three years typically consumes 8–12% of the ticket, most of the discount you thought you captured
- Buying RTM without inspecting at different hours — the 11 am sales visit hides the 6 pm traffic, the weekend society noise and the west-facing afternoon heat
- Treating the sample flat as the spec — the agreement's specification annexure is the spec; photograph the sample flat and get the annexure to match it
- Ignoring the OC vs CC distinction in 'ready' stock — a Completion Certificate is not an Occupation Certificate; without OC you carry legal-occupancy and GST ambiguity
- Choosing UC from a weak builder because the corridor is hot — corridor appreciation accrues to delivered projects; stalled ones watch it from a courtroom
- Forgetting exit rules in possession-weighted plans — 10:90 schemes usually restrict resale before OC; if your horizon is short, that 'buyer-friendly' plan is a lock-in
Quick answers to the questions buyers actually ask
- Is the GST on under-construction really unavoidable? — Yes, 5% on every instalment until OC; only OC-backed purchases escape it. Factor it into every UC-vs-RTM comparison
- How much cheaper should UC be to make sense? — After GST and double burden, we want a genuine 12%+ net discount against RTM comparables from an equal-quality builder — otherwise certainty is underpriced
- Can I exit a UC booking midway? — Usually yes with transfer charges (₹100–300/sq ft typical) and builder consent; but pre-OC resale markets are thin, so treat UC money as committed to possession
- Is nearly-ready really safer, or just marketing? — Verifiably safer if the structure is topped out and OC is applied for; the historical stall risk concentrates in the first 40% of construction
- Do banks treat UC and RTM loans differently? — Rates are similar; disbursement differs (construction-linked vs lump sum) and UC carries pre-EMI interest during the build. Your effective cost on UC is always a little higher than the rate card suggests
- What if I find a great RTM resale versus a new UC launch? — Resale RTM often wins: no GST, immediate everything, and a negotiable seller. Just budget transfer charges and verify society dues are cleared
The honest summary: certainty has become more valuable in 2026, not less — supply is abundant, but trustworthy completion is not. Pay for certainty when your life needs it; buy the discount only when the builder makes the risk boring.